
Chargeback ratiocalculator.
Enter one month of numbers. See your Visa VAMP ratio and Mastercard chargeback ratio against the 2026 thresholds, and how many more cases you can take before you’re flagged.
We cut ratios with RDR, alerts and CE3.0, and route volume across backup MIDs while you recover.
Thresholds as published for 2026. Acquirers usually set stricter internal limits. Estimates only; confirm with your acquirer’s reporting.
How the two ratios are calculated
- Visa VAMP ratio = (fraud reports + disputes − cases resolved through RDR or Compelling Evidence 3.0) ÷ settled card-not-present transactions, all in the same month.
- Visa flags a merchant as Excessive at 1.5% in the US, Canada, Europe, Asia-Pacific and Latin America, and 2.2% in CEMEA, once the merchant has at least 1,500 counted cases (CEMEA uses a lower count plus a value floor).
- Mastercard ratio = this month’s chargebacks ÷ last month’s Mastercard transactions. Excessive (ECM) at 100+ chargebacks and 1.5%; High Excessive (HECM) at 300+ and 3%.
- Acquirers are scored on their whole portfolio at 0.5% and 0.7%, which is why many set merchant limits well below Visa’s.
What is a good chargeback ratio?
Below 0.5% keeps most acquirers comfortable. Visa and Mastercard only flag at 1.5%, but acquirers manage their own portfolio limits, so expect pressure well before the scheme thresholds.
Do fraud reports count even if there was no chargeback?
Under Visa VAMP, yes. Issuer fraud reports (TC40s) and disputes are added together, so a merchant with few chargebacks but many fraud reports can still be flagged.
Why does Mastercard use last month’s transactions?
Mastercard divides current chargebacks by the previous month’s transaction count. A drop in sales volume can push the ratio up even if customer behavior hasn’t changed.
How do I lower my VAMP ratio?
Resolve disputes before they count (RDR and alerts), submit Compelling Evidence 3.0 where eligible, stop card testing, use clear descriptors and refund faster. These are the levers the scheme rules reward.
Chargeback Ratio Thresholds: Visa VAMP and Mastercard Rules for 2026
Visa's VAMP threshold dropped to 1.5% in April 2026, and Mastercard still flags merchants at 100 chargebacks and 1.5%. How each ratio is calculated, what it costs, and how to bring it down legitimately.
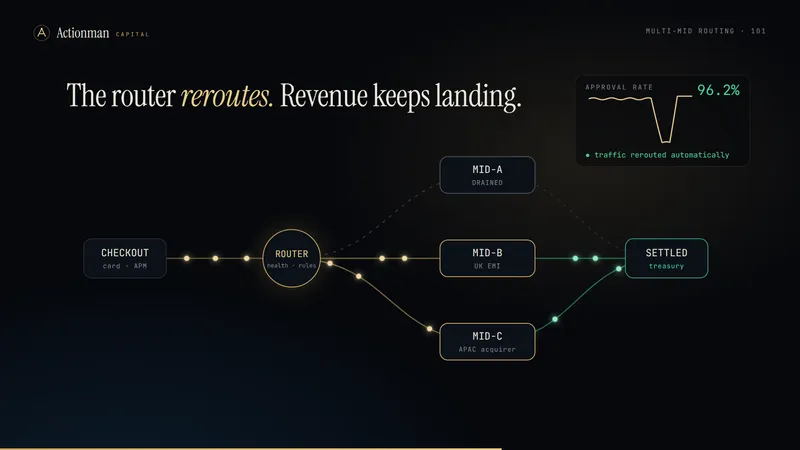
High-Risk Merchant Accounts: How Multi-MID Routing Keeps You Processing
A high-risk merchant account is one decision away from zero. How multi-MID routing and failover work, the 2026 VAMP and retry rules a router must respect, why setups still fail, and where resilience ends and MID stacking begins.
MATCH List: Reason Codes, the 5-Year Rule and How Removal Works
A Mastercard MATCH listing lasts five years and only the listing acquirer can remove it early. The reason codes, how to find out why you were listed, and the removal routes that actually work.