
Approval raterevenue calculator.
Declines are the most expensive line on your P&L that nobody reports. Put a number on every point of approval rate before you argue about basis points.
72% → 80% approval on $1,000,000 attempted per month
Smart routing, retries on the right decline codes and a second acquirer usually move approval by several points. We set it up and prove it on your traffic.
Every 1 point of approval rate is worth about $48,000 a year in gross profit at these numbers. That’s the budget for routing, retries and a second acquirer.
Where approval-rate gains come from
- Routing each transaction to the acquirer and MID most likely to approve it for that card BIN, country and currency.
- Retrying soft declines on a second route where the decline code and scheme rules allow it; never retrying hard declines.
- Local acquiring in the customer’s region, network tokens and correct 3-D Secure strategy, which issuers reward with fewer declines.
- Fixing descriptor, MCC and billing-flow issues that make issuers suspicious of legitimate payments.
What is a good card approval rate?
It depends heavily on vertical, geography and card mix. Cross-border card-not-present and high-risk verticals run lower than domestic low-risk e-commerce. Compare against your own segments over time rather than a generic benchmark.
Does payment orchestration increase approval rates?
It can, when there are multiple good routes behind it and the rules use real decline data. Orchestration over a single acquirer changes little.
Should I retry declined payments?
Only soft declines, on a limited schedule, and only where the decline code allows it. Card schemes cap retries and charge for excessive ones.
What is the difference between a soft and hard decline?
A soft decline is temporary (for example insufficient funds or a timeout) and may succeed later or on another route. A hard decline (stolen card, closed account, do-not-retry codes) should never be retried.
Payment Orchestration Platform Guide for High-Risk Merchants
How a payment orchestration platform routes, cascades and fails over across multiple acquirers, what it can and cannot fix for high-risk merchants, and a practical checklist for choosing one.
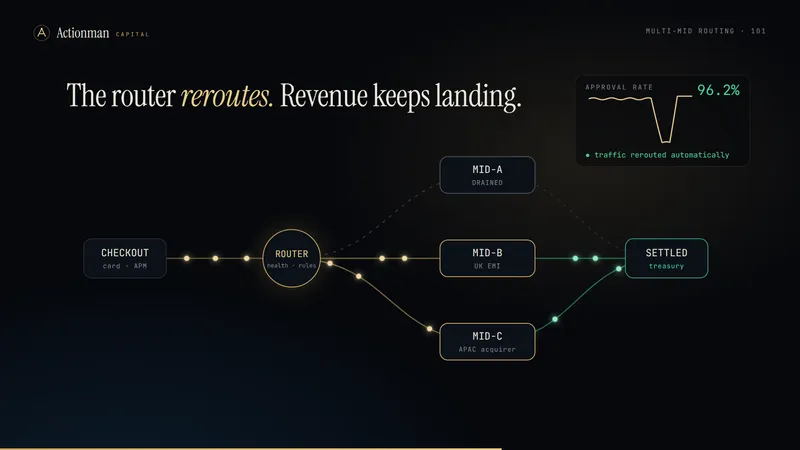
High-Risk Merchant Accounts: How Multi-MID Routing Keeps You Processing
A high-risk merchant account is one decision away from zero. How multi-MID routing and failover work, the 2026 VAMP and retry rules a router must respect, why setups still fail, and where resilience ends and MID stacking begins.
Merchant of Record vs Payment Facilitator: Liability, Tax and Fit
A merchant of record takes over the sale, including chargebacks and VAT; a payment facilitator only takes over the plumbing. How MoR, PayFac and direct merchant accounts compare, and when each fits.